Opening a Brokerage Account in Dubai: Access and Regulation
If you live in Dubai or run a company there, sooner or later you will ask about a local securities account. Access is regulated and open, but the landscape differs considerably from Europe, and the decisive question comes up before you open the account.
Understanding the regulatory landscape
The UAE has several regulatory jurisdictions side by side. If you open a brokerage account, you should know which one applies: investor protection, legal recourse and, in a dispute, the competent court all depend on it.
| Jurisdiction | Regulator | Legal framework |
|---|---|---|
| UAE mainland | SCA | UAE law |
| DIFC | DFSA | its own law, based on common law |
| ADGM | FSRA | its own legal framework in Abu Dhabi |
Accounts with internationally active firms are often held through the DIFC or ADGM. For investors from the German-speaking countries this matters, because a more familiar legal approach applies there and the courts hear cases in English.
The available routes
- Account with your main bank: many large banks offer securities services to existing customers
- Specialised brokers licensed by the SCA, DFSA or FSRA
- Access to the local market via DFM and ADX, which requires an Investor Number
- International markets via brokers with the relevant connectivity
The Investor Number for local exchanges
If you want to trade shares on the Dubai Financial Market or the Abu Dhabi Securities Exchange, you need an Investor Number. It is issued by the respective exchange and serves as the investor's unique identifier.
- Apply online or through a licensed broker
- You need your passport, Emirates ID and a local bank account
- The number is permanent and is used for every purchase and sale
- For investors without residency, access is restricted and depends on the institution
What is required to open an account
- Passport and Emirates ID
- Proof of address
- Proof of source of funds
- Information on investment experience and risk appetite
- CRS and FATCA declarations on tax residence
- For local exchanges, the Investor Number as well
The questionnaire on investment experience and risk appetite is not a formality. It determines which products the provider is allowed to offer you at all. If you fill it in too conservatively, certain instruments will not be unlocked for you later.
Currency and market access
The dirham is pegged to the US dollar. If you invest in dollar assets through an account in the UAE, you therefore have no additional currency risk compared with a dollar account elsewhere. Against the euro, however, that risk very much exists.
- Local markets are comparatively small and dominated by a few sectors
- Access to US and European markets runs through international brokers
- Trading costs are often higher than what European online brokers charge
- The range of funds and ETFs differs significantly from the European offering
Brokerage account and company: two separate levels
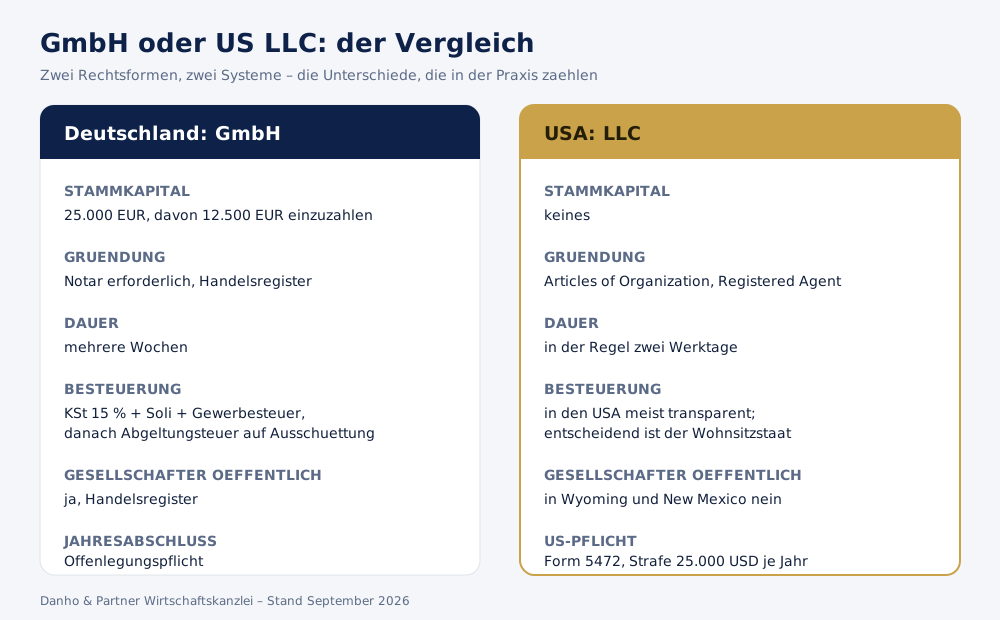
A common question is whether securities should be held through your own UAE company rather than privately. Both routes are possible, but they lead to different consequences.
- Securities held privately remain tax-free at the level of the individual, provided your tax residence is in the UAE
- Securities held through a company form part of its taxable result and may be subject to Corporate Tax
- For free zone companies there is the additional question of whether investment income counts as qualifying income
- Opening an account in the company's name requires the same documents as a corporate bank account
The blanket assumption that the company is the cheaper place to hold securities does not hold in most cases. If you are considering it, have the Corporate Tax impact calculated in advance instead of discovering it after the first financial year.
The point that matters most for German investors
In the UAE, no tax is levied on capital gains and dividends at the level of the individual. However, this only applies if you are actually tax resident there.
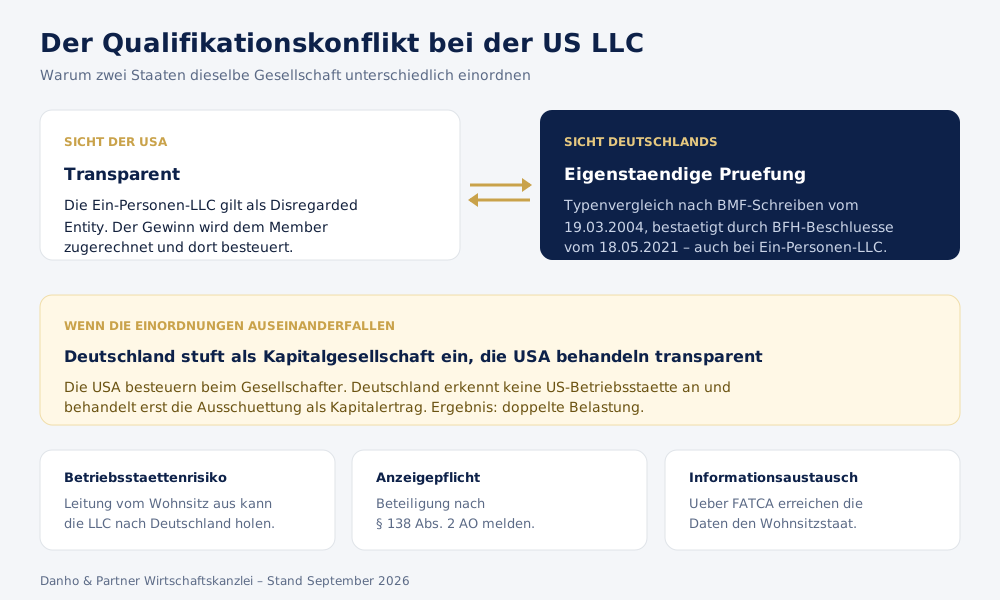
If your residence in Germany remains, the German flat-rate withholding tax (Abgeltungsteuer) continues to apply, regardless of where the account is held. Since there has been no double taxation agreement between Germany and the UAE since the end of 2021, this issue cannot be resolved through a treaty. The German tax office will learn about the account through the automatic exchange of information anyway.
There is also the practical side: a foreign account does not withhold German Abgeltungsteuer. You have to declare the income yourself, calculate capital gains yourself and prepare the supporting documents yourself, work that a domestic account does for you.
How we assess the topic
A brokerage account in the UAE makes sense if your centre of life is there. Then it is the natural place for your securities, the tax advantage at the private level actually takes effect, and the account is administered in the same place as your bank account.
If you are still resident in Germany and open an account in Dubai purely because of the tax exemption, you create extra work with no benefit. In such cases we advise against it and recommend clarifying the residence question first. Everything else follows from that.
We do not advise on the selection of specific investment products. That is a matter for licensed investment advisers, and we deliberately keep that separation.
What to clarify before opening an account
- Where are you actually tax resident?
- Which regulatory jurisdiction applies, and what does it mean for your legal recourse?
- Do you need access to local or to international markets?
- How do trading and custody fees compare with your current provider?
- Have your reporting obligations in your home country been clarified?
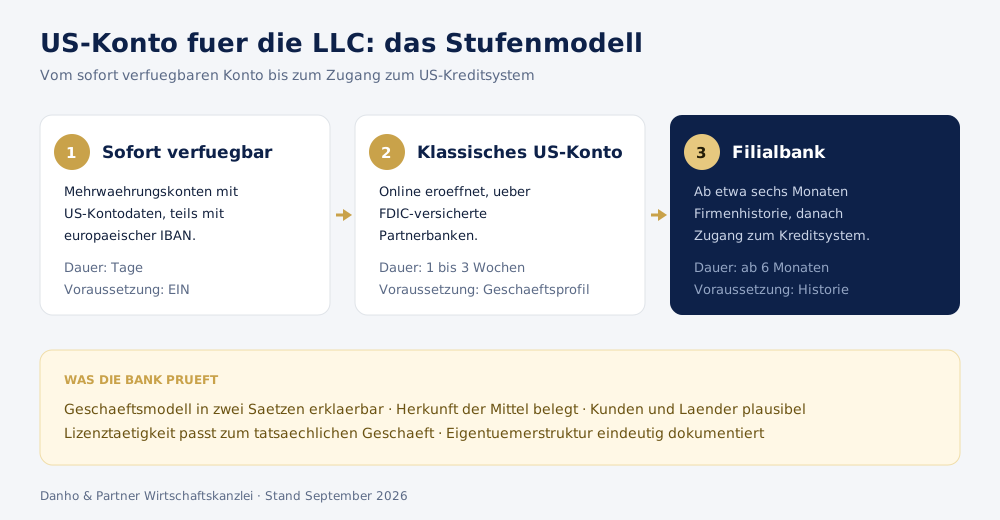
How account and structure fit together is explained under Opening a bank account in Dubai.
Firma gründen in Dubai 2026
25 Seiten zu Gründung, Buchhaltung, Steuern und Bankkonto in den VAE.
Mit dem Absenden stimmst du der Verarbeitung deiner Daten gemäß unserer Datenschutzerklärung zu. Abmeldung jederzeit möglich.
Talk to us
Get in touch to discuss your individual case. We offer detailed solutions tailored precisely to your needs.