US LLC Taxes in Germany: Entity Classification and Qualification Conflict
A US LLC is quickly set up. What happens afterwards in Germany decides whether it becomes a tool or a problem. The core lies in a question that many providers skip: how does German tax law classify this company in the first place?
The short answer
Germany does not adopt the American classification. While the US treats a single-member LLC as transparent by default, the German tax authorities independently examine whether the company resembles a corporation or a partnership. If the two classifications diverge, a qualification conflict (Qualifikationskonflikt) arises, and that can be expensive.
In the video: How the formation works, what a US LLC really costs and where German entrepreneurs regularly stumble over the qualification conflict.
The entity classification test
The decisive document is the Federal Ministry of Finance (BMF) circular of 19 March 2004, known in practice as the LLC decree (LLC-Erlass). It describes the criteria the tax authorities use to classify a foreign company (Typenvergleich, entity comparison).
- Centralised management or management by the members themselves
- Limited or unlimited liability of the members
- Free transferability of the shares
- Profit allocation and capital contribution
- Duration and dissolution of the company
None of these criteria is decisive on its own. What matters is the overall picture. With decisions of 18 May 2021, the Federal Fiscal Court (Bundesfinanzhof) confirmed that this entity comparison is decisive, expressly also for single-member LLCs. The fact that the LLC is a disregarded entity in the US plays no role here.
What follows from this
| Classification in Germany | Consequence for the member |
|---|---|
| Partnership (transparent) | Profit is attributed directly and taxed at the personal rate |
| Non-independent branch of the member | Same classification in both countries; double taxation is avoided through the tax credit |
| Corporation (non-transparent) | Qualification conflict: taxation in the US at member level, in Germany only on distribution |
The third case is the unpleasant one. The US attributes the profit to the member and taxes it there. Germany does not recognise a US permanent establishment of the member, because it sees the LLC as a separate taxpayer, and only taxes on distribution. The result is taxation twice, and the tax credit mitigates this at best.
The permanent establishment at your own desk
The second big issue has nothing to do with paperwork but with your workplace.
If the management decisions of an LLC are made at the residence of the German managing member, a permanent establishment for tax purposes (Betriebsstätte) can arise there. In the worst case, the place of effective management moves entirely to Germany; the LLC is then subject to unlimited tax liability there, even though it is registered in Wyoming.
This effect has increased considerably with the shift to working from home. If you decide every day from your kitchen table which orders to accept and which invoices to issue, you are in fact managing the company from Germany.
A worked example of the effect
A single-member LLC in Wyoming makes a profit of EUR 200,000 from consulting services for European clients. The member lives in Germany and works from there.
Without a US connection, there is generally no income tax in the US, but the filing obligations still apply. In Germany, everything depends on the classification: if the LLC is treated as transparent, the member pays tax on the profit directly at their personal rate. If it is classified as a corporation and its management is in fact in Germany, it is subject to corporate income tax and trade tax there, and the distribution is taxed on top.
With this level of profit, the difference between the two routes can run into five figures. It is not decided by you, but by the overall picture of your company.
Obligations that apply regardless
- Notification obligation: acquiring a holding in a foreign company must be reported under § 138(2) of the German Fiscal Code (Abgabenordnung, AO), regardless of how the LLC is classified
- CFC taxation (Hinzurechnungsbesteuerung): for low-taxed passive income of a controlled foreign company, §§ 7 et seq. of the Foreign Tax Act (AStG) apply. Usually not relevant for operating business, but very much so for licensing and financing structures
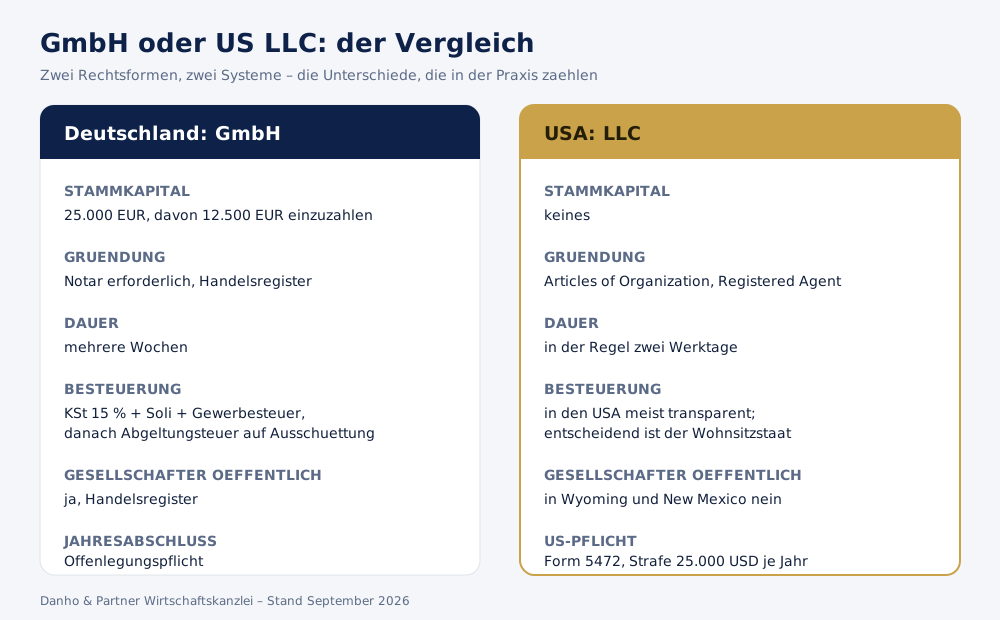
- Form 5472: on the US side, this filing is due annually for every LLC with a foreign owner. The penalty for not filing is USD 25,000 per year, even without profit
- Exchange of information: the US does not participate in the Common Reporting Standard, but exchanges data with Germany under FATCA
When an LLC makes sense in Germany at all
It makes sense as a payment and market access structure when there is a real US connection: American clients, payment service providers, marketplaces. It does not make sense as a tax-saving model for someone who lives and works in Germany.
The reason is simple: it does not change your residence. What it changes is the workload: filing obligations in two countries instead of one.
Austria and Switzerland
Both countries also assess under their national law, with their own criteria for residence, place of management and permanent establishments. The basic question is the same; the answers may differ. If you set up from Vienna or Zurich, you should have the classification clarified separately there.
How we see it
From our client work: we regularly see clients who set up an LLC through an online provider and realise two years later that neither the notification under § 138 AO nor Form 5472 was ever filed. Catching up then costs many times what ongoing support would have cost.
Pay particular attention: the classification of your LLC is not a matter of choice. It results from the operating agreement and how the company is actually run. If you sign your operating agreement without regard to the entity comparison, you leave the decision to chance and only find out the result in a tax audit.
Our advice: have the operating agreement drafted before formation with the German classification in mind. This costs one round of advice and prevents the conflict instead of resolving it later.
Clarify before formation
- Where are management decisions actually made?
- Does your operating agreement lead to classification as a corporation or a partnership?
- Is there a real US connection, or is the LLC just a shell?
- Have you planned for the notification under § 138 AO and Form 5472?
- Who handles the filings on both sides?
As of 1 September 2026. This article does not replace individual tax advice.
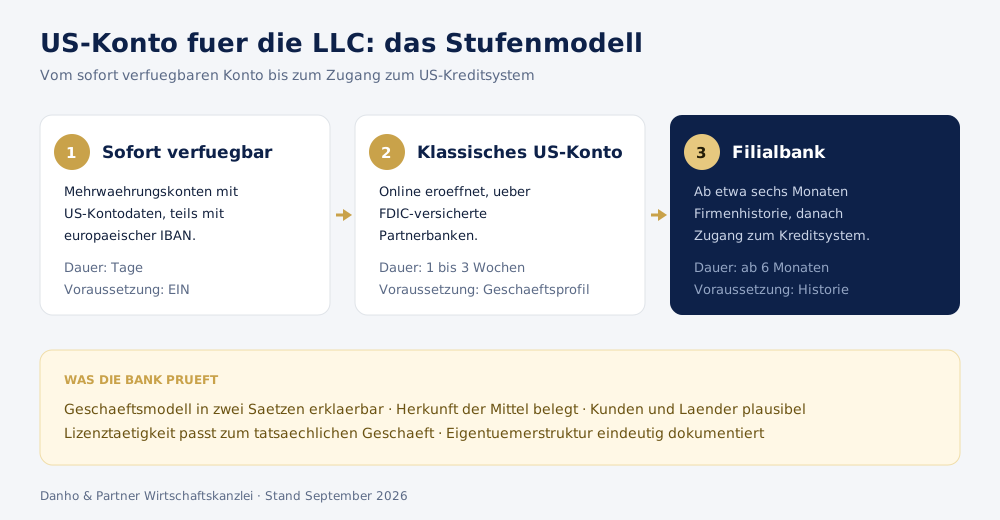
You will find an overview of the process, costs and structure on our page on the US LLC.
In addition, for location-independent entrepreneurs: the comparison of free zone company and US LLC, the account question and the risks when returning are covered on our page Digital nomad.
Firma gründen in Dubai 2026
25 Seiten zu Gründung, Buchhaltung, Steuern und Bankkonto in den VAE.
Mit dem Absenden stimmst du der Verarbeitung deiner Daten gemäß unserer Datenschutzerklärung zu. Abmeldung jederzeit möglich.
Talk to us
Get in touch to discuss your individual case. We offer detailed solutions tailored precisely to your needs.