Double Taxation Agreement (DTA) Between Germany and the UAE
Since 31 December 2021, there has been no double taxation agreement (Doppelbesteuerungsabkommen, DBA) between Germany and the United Arab Emirates. The previous agreement expired and was not renewed. If you move to Dubai today or do business from there, you are therefore operating in a space without a treaty, and that has consequences many people only notice late.
What a DTA normally does
A double taxation agreement allocates taxing rights between two states. It determines which state may tax which type of income and prevents the same income from being taxed twice. It uses two methods for this:
- Exemption: the state of residence refrains from taxing the income, usually subject to progression (Progressionsvorbehalt)
- Credit: the state of residence taxes the income but credits the tax paid in the other state
Between Germany and the UAE, neither of these methods applies any longer, because the basis for them is missing.
What has taken the treaty's place
Germany now applies national law exclusively. Double taxation is mitigated through unilateral provisions, above all through the credit for foreign taxes under Section 34c of the German Income Tax Act (Einkommensteuergesetz).
In the Germany–UAE constellation, however, this often comes to nothing. The reason is simple: where the Emirates do not levy income tax at the level of the individual, there is nothing to credit. The German tax then remains in full.
| Situation | Consequence without a DTA |
|---|---|
| Residence remains in Germany | worldwide income is taxed in Germany |
| Residence fully given up | only German-source income, but without treaty protection |
| German rental income | remains taxable in Germany |
| Dual residence | no tie-breaker rule, no mutual agreement procedure |
The point that carries the most weight: no tie-breaker rule
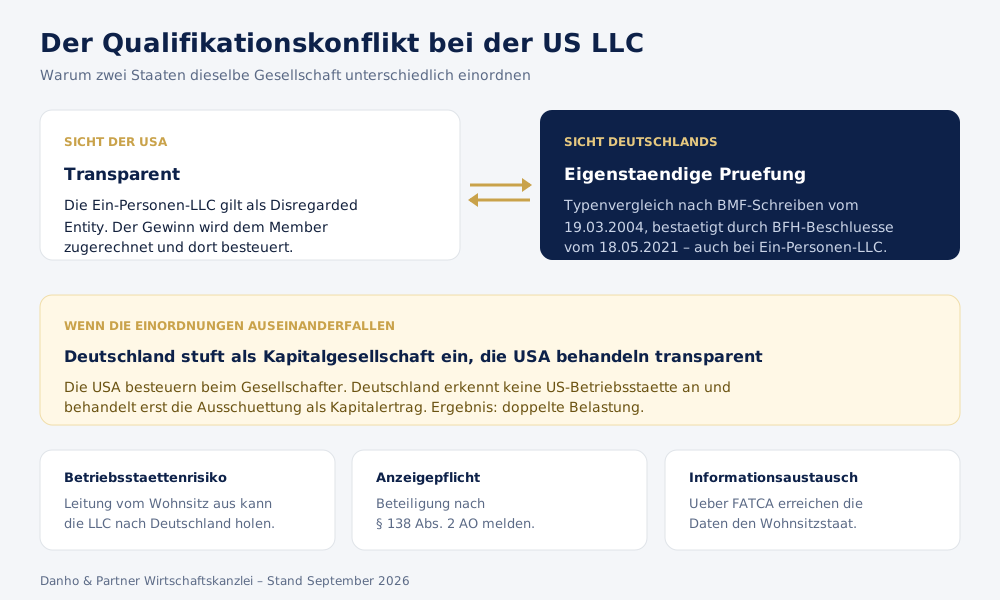
Treaties usually contain an order of priority for cases in which both states treat a person as resident: permanent home, centre of vital interests, habitual abode, nationality. That order of priority is missing here.
If there is a dispute about where you are resident, there is no rule that resolves it and no mutual agreement procedure between the tax administrations. You bear the burden of proof alone, with your tenancy contract, Emirates ID, travel dates, bank transactions and the question of where your family lives.
This is why we advise clients to keep complete documentation. A Tax Residency Certificate from the Emirates is an indication, but not proof with binding effect on the German tax office.
What the end of the treaty means in concrete terms
- No reduction of withholding tax: dividends, interest and royalties from German sources are subject to the full national rate, without the reductions usual under a treaty
- No exemption for permanent establishment profits: a permanent establishment in the Emirates does not automatically lead to an exemption in Germany
- No treaty rules for pensions: allocation follows national law alone
- No treaty 183-day rule: the familiar rule for employees does not apply here
CFC taxation and extended limited tax liability
Two German provisions continue to apply without any treaty restraint.
CFC taxation (Hinzurechnungsbesteuerung) under the German Foreign Tax Act (Außensteuergesetz, AStG) attributes the profits of a low-taxed foreign company to the controlling shareholder where passive income exists, regardless of whether profits have been distributed. For a free zone company taxed at 0%, the low-taxation test is regularly met; what then matters is whether the income is active and whether there is substance on the ground.
Extended limited tax liability (erweiterte beschränkte Steuerpflicht) under Section 2 AStG can continue to apply for up to ten years after emigration if significant economic interests remain in Germany and the destination country has low taxation. Both apply to the Emirates.
What follows for practice
The end of the treaty does not make the location worse, it makes planning more demanding. If you relocate your residence cleanly, actually live in the UAE and back the structure with substance, the missing treaty is no disadvantage to you.
If, on the other hand, you live half here and half there, you lose the instrument that would otherwise resolve such cases. It is precisely in this grey area that expensive proceedings arise.
What a new treaty would change
There is repeated speculation about renegotiation. There are currently no reliable statements on this. If you are planning today, you should therefore start from the existing situation and not count on a future arrangement.
If a new treaty were concluded, it would ease the situation mainly in three respects: an order of priority for residence, reduced withholding taxes on dividends and interest, and a mutual agreement procedure for disputes. Until then, national law applies on both sides.
For Switzerland and Austria, the situation is different: both countries have a treaty with the Emirates. If you move from these countries, you are therefore working within a different framework from German clients.
How we assess it
From our client work: the missing treaty is rarely the real problem. It becomes a problem when the move only takes place on paper: visa yes, home no; company yes, decisions still made from Germany.
Our division of roles: we build and document the UAE side, including licence, bank account, Emirates ID and evidence of actual presence. Assessing the German consequences remains with your tax adviser there. On request, we coordinate with them directly.
Our advice: have the conversation with your German adviser before the move, not afterwards. And start a file from day one: travel dates, tenancy contract, bank statements, Emirates ID. These documents take ten minutes today and, if in doubt, decide amounts in the six figures.
What to clarify before moving
- Will your German residence be given up completely, or will a home remain available?
- Where is your family's centre of life?
- Do you hold shares of one per cent or more in a German corporation?
- Does your UAE company earn active or passive income?
- Will significant economic interests remain in Germany?
As of: 28 August 2026. This article does not replace individual tax advice.
How to build a structure in the Emirates around this is explained on our page on tax planning.
Firma gründen in Dubai 2026
25 Seiten zu Gründung, Buchhaltung, Steuern und Bankkonto in den VAE.
Mit dem Absenden stimmst du der Verarbeitung deiner Daten gemäß unserer Datenschutzerklärung zu. Abmeldung jederzeit möglich.
Talk to us
Get in touch to discuss your individual case. We offer detailed solutions tailored precisely to your needs.