Setting Up a Company in Dubai While Living in Germany: What Really Happens for Tax Purposes
Setting up a company in Dubai while continuing to live in Germany is legally possible, but it is the most demanding constellation of all. The company then sits between two tax systems, and both of them lay claim to it.
What applies in this constellation
The company formation itself does not require residence in the Emirates. A free zone company can be registered even if you remain registered as a resident in Germany. The question is not whether it works, but what consequences it has.
| Level | Germany | UAE |
|---|---|---|
| Personal tax liability | continues while you keep your residence | no personal income tax |
| Company | CFC attribution where applicable | 0% or 9% corporate tax |
| Place of management | decisive | decisive |
| Double tax treaty | none since the end of 2021 | none since the end of 2021 |
The place of management decides
A company is taxed where it is actually managed, not where it is registered. If you make the decisions from your desk in Germany, you risk the German tax office (Finanzamt) treating the company as resident in Germany. The decisive concept is the place of effective management (Ort der Geschäftsleitung).
- Where are contracts negotiated and signed?
- From where are employees instructed and prices set?
- Where do shareholder meetings take place and how are they minuted?
- How many days a year are you actually on site?
These questions determine where the company is taxed. A licence and a flexi desk are not enough if management demonstrably sits elsewhere.
CFC taxation under the German Foreign Tax Act
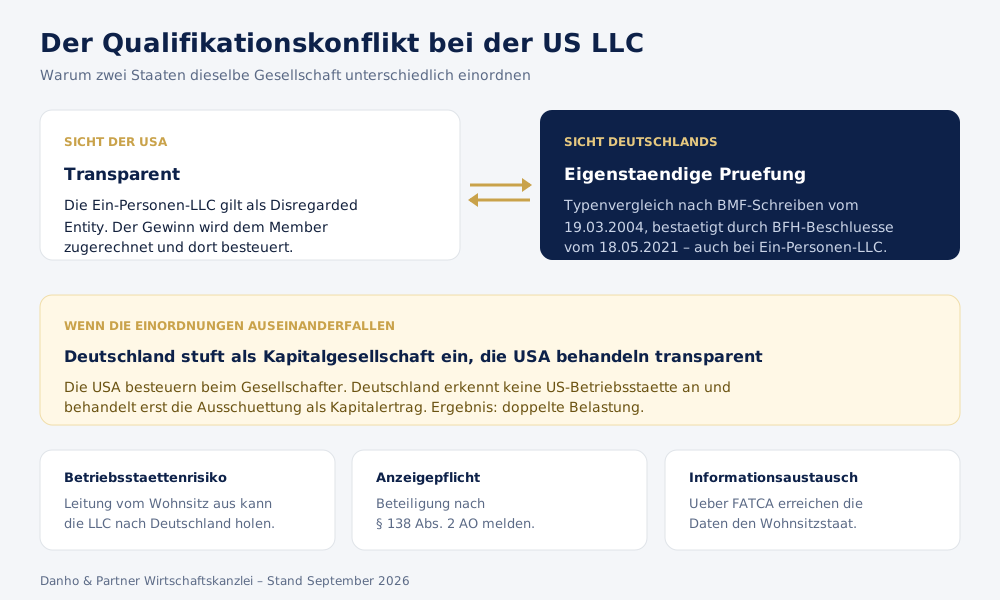
If a person resident in Germany holds a majority in a low-taxed foreign company that earns passive income, the rules on CFC taxation (Hinzurechnungsbesteuerung) under the German Foreign Tax Act (Außensteuergesetz, AStG) apply. The profits are then attributed to the shareholder and taxed in Germany, regardless of whether they were distributed.
Passive income includes, among other things, interest, licence income and certain services provided to related parties. Active business with genuine substance on the ground is generally not covered. Exactly where the line lies is a case-by-case question and should be reviewed by your German adviser.
No double tax treaty
Since 31 December 2021 there has been no double tax treaty (Doppelbesteuerungsabkommen) between Germany and the UAE. This removes the instrument that would otherwise resolve double taxation. If the same income is taxed in both countries, there is no rule giving either of them priority.
That is why this constellation requires more care than a company formation combined with a complete move abroad. With a genuine relocation, the question does not arise in the first place.
Substance: what authorities and banks mean by it
Substance is the concept on which the entire constellation hinges. It means that the company actually does business where it is registered. For the UAE tax authorities this matters when the 0% rate of a free zone company is claimed; for the German tax office it matters when CFC attribution is at stake.
- An office that goes beyond a mere mailing address
- Staff on site or services demonstrably performed there
- Costs that match the claimed activity: rent, salaries, licence fees
- Decisions that are documented as being taken on site
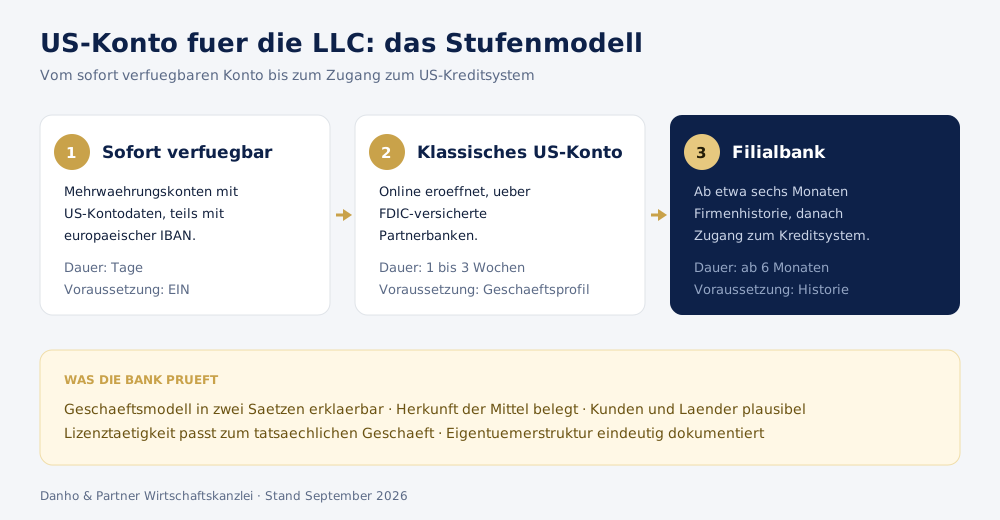
- A bank account in the Emirates through which payments actually run
The more of these points are met, the more robust the structure is. Conversely, if you cannot show a single one of them, you have a company that will not withstand an audit, neither in Germany nor in the Emirates.
Building substance costs money and requires presence. This is exactly the point at which it is decided whether a company formation without relocation still makes economic sense, or whether a complete move is ultimately the simpler route.
When the constellation can still work
- As a shareholding in a company that is run by partners on the ground
- As a minority shareholding without controlling influence
- With operating business backed by genuine substance in the Emirates: office, staff, decisions on site
- As preparation for a later move, with a clear timeline
What goes wrong in practice
- The company exists only on paper, while the business continues to run from Germany as before
- Invoices go to the same German customers as before, just with a different letterhead
- There are no staff and no decisions on site
- The bank refuses the account because the business model shows no connection to the Emirates
The last point hits fastest: even before the tax office asks questions, the structure fails at the account opening stage.
How we assess this constellation
If you stay resident in Germany and expect a Dubai company to lower your tax burden, you will be disappointed in most cases. The savings that are advertised require an actual move abroad, not just a registration.
A company formation without relocation makes sense when there is a genuine business reason behind it: a market in the region, partners on the ground, a base for international clients. Then the structure holds, because it follows a purpose rather than a tax expectation.
Our advice: first clarify with your German tax adviser (Steuerberater) what a move abroad would mean for you. Only once that question is answered does it make sense to talk about the structure in the Emirates. We provide the documents for that conversation and, if you wish, coordinate directly with your adviser.
Clarify before you decide
- Will your residence in Germany remain in place permanently?
- Who makes the business decisions, and from where?
- Is the income active or passive within the meaning of the Foreign Tax Act?
- Do you hold shares of one percent or more in a German corporation?
- Can you build and document substance in the Emirates?
We have summarised how a company formation in Dubai works and which structures are available on a separate page.
Firma gründen in Dubai 2026
25 Seiten zu Gründung, Buchhaltung, Steuern und Bankkonto in den VAE.
Mit dem Absenden stimmst du der Verarbeitung deiner Daten gemäß unserer Datenschutzerklärung zu. Abmeldung jederzeit möglich.
Talk to us
Get in touch to discuss your individual case. We offer detailed solutions tailored precisely to your needs.